The global semiconductor industry maintains a positive trajectory, propelled by the rapid evolution of Artificial Intelligence (AI) and strong demand across various sectors. With manufacturing sentiment improving and the semiconductor BSI hitting a record high, expectations for an industry recovery are robust. Explore the key trends in the semiconductor industry with JADISS market analysis.
Keywords
Flow
Shorts
The semiconductor industry has recently shown a positive atmosphere, aligning with the overall economic recovery. The proliferation of Artificial Intelligence (AI) technology is acting as a key driver for semiconductor demand, leading to increased data center expansion and high-performance computing (HPC) requirements. The Business Survey Index (BSI) for the semiconductor sector reaching an all-time high within the manufacturing BSI reflects the robust demand from these downstream industries and companies' high expectations for industry improvement.
This positive trend is creating ripple effects across the entire semiconductor value chain. Memory and system semiconductor manufacturers are expanding the production of AI-related high-performance products, which naturally leads to increased orders for semiconductor equipment and materials industries. In particular, as competition for semiconductor factory expansion and advanced equipment adoption intensifies, the demand visibility for equipment manufacturers is improving, and the importance of post-processing and packaging technologies is also highlighted, expanding growth opportunities for related companies.
The future scenario for the semiconductor industry will largely depend on the investment plans of major big tech companies and the broader macroeconomic environment. If large-scale hardware investments for AI infrastructure continue, stable semiconductor prices and robust industry growth are expected. However, macroeconomic variables such as global interest rate hike trends or geopolitical risks could act as potential downside pressures, requiring continuous monitoring. Supply chain stabilization and competition in advanced technology development will also be crucial checkpoints.
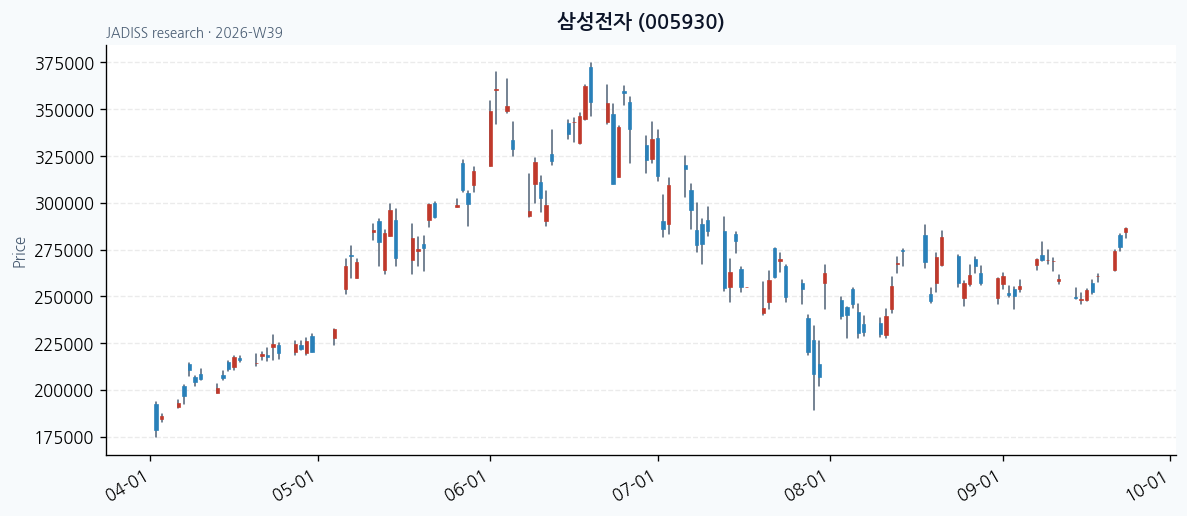
From a technical perspective, if the overall positive momentum of the industry is maintained, major semiconductor-related stocks may continue to attempt to break above their moving averages. However, if short-term overheating signals (e.g., RSI entering overbought territory) appear, temporary corrections should be considered, which can be interpreted as healthy adjustments for trend strengthening.
We maintain a positive outlook if the overall improvement trend in the semiconductor industry continues and major big tech companies' AI investment momentum persists. Specifically, if increased demand for high-performance semiconductors and price stabilization are confirmed, a holding strategy can be considered.
If signs of an industry slowdown become clear, such as a deepening global economic recession, accelerated interest rate hikes in major countries, or increasing semiconductor inventory and downward pressure on prices, a conservative approach to the industry as a whole should be considered, reviewing scenarios for reducing exposure or selling.
If this hits
- 주요 빅테크 기업들의 AI 관련 데이터센터 투자 확대 계획 발표
- 고성능 메모리 및 시스템 반도체 신규 주문 증가 및 가격 상승
- 글로벌 경제 지표 개선 및 소비 심리 회복으로 전방 IT 기기 수요 증대
- 차세대 반도체 기술(예: HBM, 온디바이스 AI) 상용화 가속화
If this breaks
- 글로벌 경기 침체 심화 및 주요국 금리 인상 가속화
- 주요 반도체 기업들의 재고 증가 및 가격 경쟁 심화
- 예상치 못한 지정학적 리스크 심화로 인한 공급망 불안정
- 빅테크 기업들의 투자 계획 축소 또는 지연
Watch
- 주요국 제조업 구매관리자지수(PMI) 및 반도체 출하량 지표
- 글로벌 빅테크 기업들의 분기별 실적 발표 및 투자 가이던스
- 반도체 D램 및 낸드플래시 고정거래가격 변동 추이
- 미국 연방준비제도(Fed)의 통화정책 방향 및 금리 인상 속도
- 인공지능(AI) 관련 신기술 개발 및 시장 침투 속도
Value chain
- 메모리 반도체 제조: D램, 낸드플래시 등 저장 장치 생산
- 시스템 반도체 설계 및 제조: CPU, GPU, AP 등 연산 장치 개발 및 생산
- 반도체 장비 산업: 노광, 식각, 증착 등 공정 장비 공급
- 반도체 소재 산업: 웨이퍼, 포토레지스트, 특수가스 등 재료 공급
- 파운드리: 팹리스 기업의 설계에 따라 반도체 위탁 생산
View
Related
AI-Driven Demand Fuels Semiconductor Growth
The semiconductor industry is currently experiencing a positive surge, with the widespread adoption of Artificial Intelligence (AI) technology acting as a primary catalyst. The escalating demand for data center expansion and high-performance computing (HPC) reflects strong corporate expectations for industry improvement, evidenced by the semiconductor sector's Business Survey Index (BSI) reaching an unprecedented high.
Expanding Opportunities Across the Value Chain
This favorable trend is creating significant ripple effects throughout the entire semiconductor value chain. Increased production of AI-related high-performance products by memory and system semiconductor manufacturers is directly boosting orders for semiconductor equipment and materials. As competition for factory expansion and advanced equipment intensifies, equipment suppliers are seeing improved demand visibility, and growth opportunities are expanding for companies specializing in post-processing and packaging technologies.
Big Tech Investments and Macroeconomic Factors as Key Drivers
The future trajectory of the semiconductor industry will largely depend on the substantial hardware investment plans of major big tech companies for AI infrastructure and the broader macroeconomic environment. Sustained investment is expected to lead to stable semiconductor pricing and robust industry growth. However, macroeconomic variables such as global interest rate trends or geopolitical risks warrant continuous monitoring. JADISS provides in-depth analysis of these critical factors.
Next step
JADISS channels
Journal
· Home
· Lab
· Blog
· Telegram
Discover deeper insights and market trends with JADISS daily trading journals and weekly research briefs.
JADISS brief · Disclaimer